
Turning Customer Signals Into Retention Action
How Performix turned customer-satisfaction surveys into a closed-loop retention process, connecting feedback, risk identification and relationship-manager action for the bank’s highest-value small-business customers.
THE BUSINESS IDEA Customer feedback creates value only when someone acts on it. Wells Fargo did not need another satisfaction report. It needed to know which valuable relationships were at risk, who owned each one, and whether intervention worked. Performix built the backend that turned survey responses into that operating loop. |
Executive Snapshot
Client | Wells Fargo |
Industry | Small-Business Banking |
Business Challenge | Low satisfaction among small-business customers put high-value relationships at risk. |
Target Segment | Small-business customers with more than $1M in account balances or assets. |
Performix Role | Technical partner to BI Worldwide (the prime partner), responsible for the backend solution, data processing, risk identification and routing. |
Performix Solution | Phone and email surveys of about 10 questions, scored to flag at-risk customers, routed to the responsible branch manager or Business Relationship Manager, and re-measured after intervention. |
Business Outcome | Substantial change in California within about two months; expanded to approximately 25–26 western states within about six months. |
Why this case matters: Most satisfaction programs stop at measurement. This one assigned every at-risk customer to a named owner and then checked whether the experience improved, which is what turns a churn signal into a retention action.
1. The Business Challenge
Wells Fargo’s small-business segment faced a satisfaction problem, and the customers most exposed were also among the most valuable: businesses holding more than $1 million in balances or assets. Losing even a few of these relationships carries a significant revenue cost.
The bank could measure satisfaction. What it lacked was a reliable way to turn that measurement into timely action by the people who own the relationship.
THE KEY QUESTION How can the bank identify at-risk customers early enough for the relationship team to do something about it, and then confirm the intervention worked? |
2. Performix’s Role
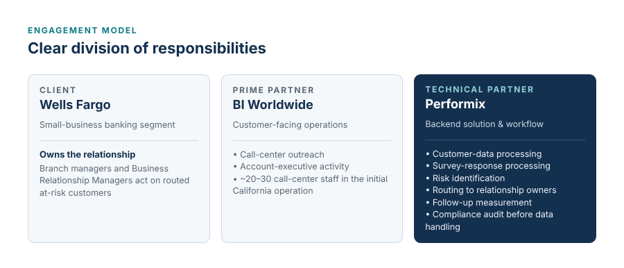
Performix was the technical partner to BI Worldwide, the prime partner on the engagement. Responsibilities were split cleanly:
Partner | Responsibility |
BI Worldwide | Customer-facing operations: call center and account-executive activity. |
Performix | Backend solution, customer-data and survey-response processing, risk identification, routing to relationship owners, and follow-up measurement. |
Because the program handled private customer financial information, Performix completed a compliance audit before receiving any customer data.
3. How the Solution Worked
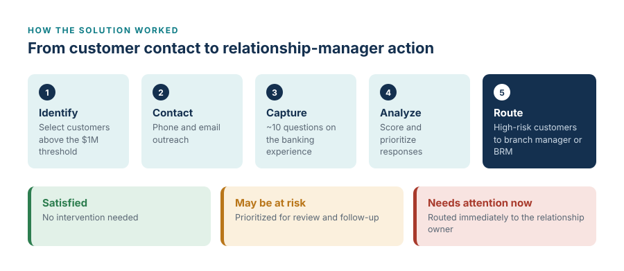
The process ran as one continuous flow from customer contact to relationship-manager action:
- Identify the population — select small-business customers above the $1M threshold.
- Contact — reach customers by phone and email; the initial California call center had roughly 20–30 staff.
- Capture — record responses to about 10 questions on the banking experience.
- Analyze and prioritize — sort customers into satisfied, potentially at risk and needing attention now.
- Route — pass high-risk customers to the appropriate branch manager or Business Relationship Manager.
4. The Intervention Loop
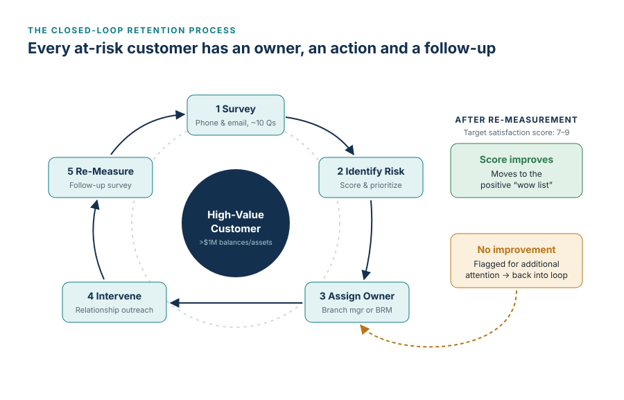
Routing was the start of the loop, not the end. The responsible relationship team contacted the flagged customer and worked on the issue, after which the customer was surveyed again.
The program targeted a satisfaction score in the 7–9 range. Customers whose scores improved moved onto a positive “wow list”; customers whose scores did not improve were flagged for further attention, keeping them in the loop until the relationship was addressed.
THE LOOP Survey → Identify Risk → Assign Owner → Intervene → Re-Measure → Escalate or Celebrate |
5. Scale & Business Impact
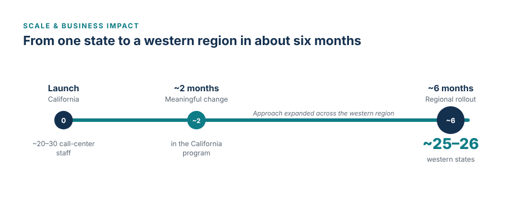
FROM ONE STATE TO ~25–26 WESTERN STATES IN ABOUT SIX MONTHS The California program showed meaningful change within roughly two months, and the approach was rolled out across approximately 25–26 western states within about six months. |
Risk visibility | At-risk, high-value customers were identified from structured feedback rather than anecdote. |
Ownership | Every flagged customer was routed to a named relationship owner. |
Accountability | Re-measurement showed whether each intervention worked. |
Scalability | A process proven in one state expanded regionally within months. |
6. The Technology Pattern
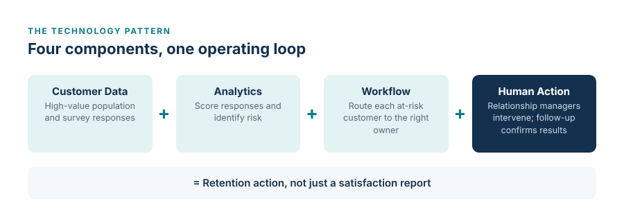
The value came from connecting four components into one operating loop rather than from any single component.
Layer | Business Purpose |
Customer Data | Define the high-value population and hold survey responses. |
Analytics | Score responses and identify risk. |
Workflow | Route each at-risk customer to the right relationship owner. |
Human Action | Relationship managers intervene; follow-up surveys confirm results. |
7. Why the Approach Worked
- Problem-led design: Built around a business risk (losing high-value relationships), not around a survey tool.
- Clear ownership: Every risk signal had a named person responsible for acting on it.
- Closed-loop measurement: Follow-up surveys showed whether action changed the outcome.
- Repeatable process: A defined workflow allowed a single-state program to scale across a region.
8. Executive Takeaway
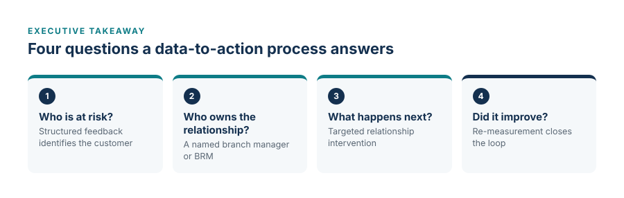
THE LESSON Customer analytics creates business value only when it leads to action. Performix helped Wells Fargo answer four questions for every high-value customer: Who is at risk? Who owns the relationship? What should happen next? Did the experience improve? |
The lesson applies to any organization that collects customer feedback: measurement alone does not retain customers. Connecting the signal to an owner, an action and a follow-up does.
The Performix Principle
Start with the business bottleneck. Understand the people and workflows around it. Then design technology that makes the process work better.
Business problems first. Technology that moves the business forward.
Business problems first.
Technology that moves business forward.
Performix helps organizations solve complex technology challenges through software engineering, data, analytics, cloud, AI, and application development.